One study found that direct peer transactions account for over 40% of reported marketplace losses—a stark reminder that user checks matter as much as platform design.
In person-to-person exchanges, users trade directly and carry more of the verification burden than on one-click exchanges. That reality shapes every safety rule readers should follow.
This guide helps UAE participants use repeatable, platform-agnostic controls: verify identities, confirm payments in a verified account, keep all chat on-platform, and keep a full evidence trail. Escrow protection and verified payment are core safeguards, but independent confirmation is essential.
The article previews: a pre-trade checklist, payment and verification rules, common scam patterns, red flags, instant actions during a trade, and recovery steps if something goes wrong. For a deeper primer on how escrow and dispute tools work, see this overview on secure P2P practice: unlocking the secrets of crypto P2P.
Key Takeaways
- Verify payments directly in the recipient account before releasing funds.
- Keep all communication on-platform to preserve evidence for disputes.
- Use escrow and identity checks as baseline safeguards.
- Document every step: timestamps, receipts, and chat logs.
- Do not follow off-platform instructions or rely on screenshots alone.
Why P2P Crypto Trading in the UAE Carries Higher Scam Risk
The mechanics of direct exchanges are simple: one person sends fiat and the other releases digital assets. An escrow can hold the asset, but it does not verify that a bank transfer settled in the recipient’s account.
Where trust breaks down: users often accept screenshots, SMS alerts, or verbal claims as proof instead of confirming a settled payment in their own bank or e-wallet. That gap is where many schemes operate.
Why urgency and attractive rates matter
Scammers push a “better rate if you hurry” narrative to compress decision time. This tactic discourages verification, nudges users off-platform, and raises the chance of error—especially near order expiry or during appeals.
The UAE market’s fast deals, multilingual chats, and frequent cross-border payments increase confusion. Treat every counterparty as unverified until platform signals and a confirmed settlement appear.
- Mechanics: fiat payment vs. asset release; escrow ≠ payment confirmation.
- Common triggers: rushed timelines, unusually favorable rates, and requests to continue off-platform.
- Mindset: verify first, trust later—document every step.
For a longer primer on secure practice and escrow mechanics, see this beginner’s guide: beginners guide to p2p trading.
Pre-Trade Safety Checklist Before You Open an Order on Any P2P Platform
Check the platform features before you commit. A reputable platform shows an escrow that locks assets during the order, a visible appeal path, and clear merchant or advertiser labeling.
Keep all messages inside the order chat so support can validate the timeline if a dispute arises. Do not move conversations to external apps.
How to screen counterparties
Verify user reputation and transaction history before accepting an offer. Look at completed transactions, completion rate, and average release time.
Only proceed when an advertiser or merchant shows identity verification. Match the payer name on payment details to the verified profile name when possible.
Harden your accounts and defenses
Enable 2FA on every account and use a strong, unique password. Set an anti-phishing code where the platform offers one to spot legitimate emails and alerts.
Keep device software updated and avoid public Wi‑Fi when placing orders. Impersonators often use phishing messages claiming an urgent freeze to force early release.
Checklist summary
- Platform: escrow lock, appeal workflow, merchant labels.
- Counterparty: completed trades, completion rate, verified advertiser status.
- Identity: name match on payment details and verified profile.
- Account security: 2FA, anti-phishing code, strong passwords, device hygiene.
- Evidence plan: prepare screenshots and downloadable logs before payment.
| Requirement | Why it matters | What to check | Action if missing |
|---|---|---|---|
| Escrow locking | Prevents asset release before dispute resolution | Order shows “locked” status during payment window | Do not open order; choose another platform |
| Appeal workflow | Enables formal dispute and evidence submission | Visible support link and dispute button in order chat | Contact support before trading or avoid the listing |
| Verified advertiser | Improves traceability and reduces anonymous abuse | Badge or label and identity verification status | Request additional proof or cancel the trade |
| Anti-phishing code & 2FA | Protects accounts from impersonation and access theft | Set code in security settings and enable MFA | Harden account before placing any orders |
Crypto P2P Trading Fraud Prevention Tips for Payments, Verification, and Escrow
Before releasing assets, verify that the exact payment has settled in the recipient’s account. A screenshot or SMS is not the same as cleared funds. Confirm the amount posts to the seller’s bank account or e‑wallet balance before you release any assets held in escrow.
Confirm settled payments, not notifications
Some transfers show “pending” or “processing.” Those states do not guarantee the recipient controls the funds. Wait for a settled balance in the bank or e‑wallet.
Enforce name‑matching and refuse third‑party money
Match the payer/payee name to the counterparty’s verified identity. Refuse third‑party payments even if an offer seems attractive—chargebacks and identity mismatches are common.
Keep every message inside the order chat
Store order ID, timestamps, payer name, amount, and method inside the platform chat. If a counterparty pushes external channels (Telegram, WhatsApp), treat that as a risk signal and keep all key information on the platform to preserve eligibility for support.
- Release rule: only after the agreed funds post to the bank account or e‑wallet.
- Escrow note: escrow locks the asset but does not confirm fiat settlement.
- Record control: save receipts, timestamps, and chat logs while the order is active.
Common P2P Crypto Scam Schemes to Recognize in Real Time
A concise pattern library helps sellers and buyers identify schemes the moment they appear. Recognizing common scams in real time reduces harm and speeds proper response.
Fake receipt and edited images
Scammers post forged screenshots to simulate payment. Always check the bank or wallet ledger directly before releasing assets; images can be altered or reused.
Phony escrow claims and release pressure
Some claim the fiat will clear after you release. Platforms do not escrow fiat—release only after confirmed settlement.
Mutual‑agreement manipulation
Clicking a mutual agreement during appeals can cancel an order and free the asset. Use it only when a verified refund is confirmed.
Impersonators, triangle, and MitM via external channels
Impostors posing as customer support ask for OTPs or off‑platform steps. Triangle and man‑in‑the‑middle schemes reuse proof across orders and break the evidence chain. Keep all chat on the platform.
| Scheme | How it works | Red flag | Action |
|---|---|---|---|
| Fake receipts | Edited images claim payment | Screenshots instead of ledger entries | Verify in bank app; refuse release |
| False escrow promise | Claims funds will show after release | Pressure to release early | Release only after settled funds |
| Mutual agreement abuse | Appeal option cancels order | Urgent request to agree | Use only with confirmed refunds |
| External channel MitM | Moves chat to WhatsApp/Telegram | New bank details or copied receipts | Refuse off‑platform, keep evidence |
| Chargeback/check & SMS spoof | Reversible payments or fake alerts | Bank SMS claims without ledger proof | Avoid checks; log into account to confirm |
Red Flags That Signal You Should Pause, Document, and Walk Away
Certain behaviors during a deal should trigger an immediate pause and evidence capture. These signs flag increased risk and reduce the chance that support can help later.
Pressure tactics, aggressive language, and rushed countdowns
Scammers often use urgency and insults to force a quick decision. A fast time pressure short-circuits proper bank checks and pushes reliance on screenshots or SMS alerts.
“Pause, gather evidence, and refuse off-platform requests — speed is a favorite tool of attackers.”
Requests to share personal information or move the deal off-platform
Moving chat to Telegram or WhatsApp is a major red flag. Off-platform messages break the evidence chain and enable impersonation or man‑in‑the‑middle schemes.
- Pause criteria: countdowns, insults, threats, and urgent price changes.
- Never share: OTPs, bank screenshots, account passwords, or other sensitive personal information.
- Safe script: remain neutral, state platform rules (name match, on‑platform chat, confirmed funds), then end the trade if terms change.
| Red flag | Why it matters | Immediate action |
|---|---|---|
| Rushed countdown | Blocks proper bank verification | Pause and request ledger proof |
| Off‑platform request | Loss of dispute evidence | Refuse and keep chat on platform |
| Demand for personal info | Enables account takeover | Decline; document and report |
Before leaving, capture the chat, user profile, and order screen so the platform can investigate patterns if you become a victim of a scam.
How to Trade Safely During the Transaction Window
When money moves and an asset sits in escrow, clear evidence becomes the primary defense for both parties. Record the order state, the chat, and any payment lines as they happen. These records make a dispute resolvable and protect a seller or buyer in UAE banking contexts.
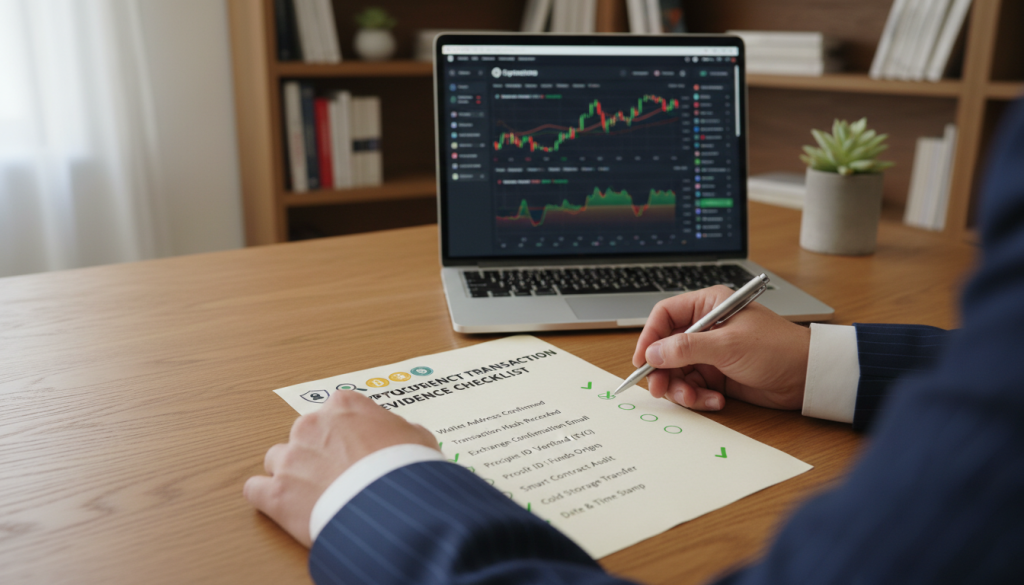
What to screenshot and store as evidence for disputes
Evidence checklist: capture the order page (amount, rate, order ID, countdown), the full in‑platform chat, and the payment instructions shown inside the order.
Also save the bank account or e‑wallet transaction line that shows a posted or settled status, timestamp, and sender name. Do not expose full balances or unnecessary personal data.
Handling mismatched payment details, partial payments, and reused receipts
Detect mismatches by comparing the payer name, amount, and receiving bank account to the order details. If any field differs, pause and document.
For partial payments: a seller must not release escrow until the full funds arrive. Log partial receipts in chat and request a clear timeline before escalating.
Reused receipts can be genuine but unrelated. Match receipt timestamps and sender identity to the order window before accepting them as proof.
When to mark paid, when to release, and when to refuse changes
The buyer should mark “paid” only after sending the agreed payment. The seller should release escrow only after confirming settled funds in the bank or e‑wallet.
Refuse mid‑trade changes: do not switch payment methods, change the payer, or split transfers unless pre‑agreed. If the counterparty insists on off‑platform contact or a cancellation after payment, involve platform support immediately and follow the platform’s off-site communication guidance: off-site communication guidance.
What to Do If You Suspect Fraud or Become a Victim
If a deal feels wrong, stop and switch to an incident response routine that preserves proof and limits loss.
Immediate steps: do not release assets, keep all messages in the platform chat, and open an appeal before the order window ends.
How to file an appeal and what to send
Submit an appeal with clear evidence so specialists can act. Include the order ID, full chat screenshots, and a bank or e‑wallet receipt that shows posted funds with the payer name.
- Order ID and timestamps
- Complete chat transcript screenshots
- Ledger line showing settled payment and payer identity
Handling impersonators and phishing without escalating risk
Do not reply with OTPs or sensitive details. Do not click unknown links. Verify sender authenticity via official support channels and confirm anti‑phishing codes before trusting emails.
When a buyer requests cancellation after payment
Do not cancel if payment shows posted. Document the request in chat and escalate via appeal so escrow stays locked until platform support resolves the transaction.
“Fast, calm documentation improves outcomes: it lets platform teams verify events with logs and user evidence.”
For wider context on consumer exposure to online scams, see this consumer bulletin on scams.
Conclusion
Safe practice begins with a single check — verify the recipient’s posted bank ledger before completing any deal.
Confirm a settled bank transfer, refuse third‑party payments, and keep every message on the platform. These simple rules protect users in UAE markets more reliably than memorizing every scheme.
Platforms help: escrow locks assets during orders, dispute tools preserve rights, and reputation metrics surface reliable counterparties. Pair those features with identity matching and clear documented evidence.
Protect accounts with 2FA and anti‑phishing measures, and always validate any support contact via official channels. For a practical primer on how escrow and platform controls work, see this guide to p2p.
If an action conflicts with verified payment, verified identity, and on‑platform records, walking away is the safest trade.