Surprising fact: in many major markets, regulators now expect peer-to-peer venues to meet the same compliance duties as formal exchanges — including KYC, AML and recordkeeping.
This shift changes how platforms operate. What once promised direct access and speed now faces new duties: onboarding, monitoring and reporting. These duties shape which payment methods are allowed and how fast users can start.
For UAE users and businesses, aligning with these expectations matters even when activity crosses borders. Clear rules improve security and build trust, while consistent processes help platforms withstand audits and investigations.
This article explains the trends and practical consequences for platforms, exchanges and users. It is informational, not legal advice — jurisdictions differ, so verify local laws before acting.
Key Takeaways
- Regulators increasingly treat P2P venues like exchanges for compliance duties.
- Onboarding speed, payment options and dispute handling are affected by rules.
- UAE-aligned choices matter for platforms serving regional users.
- Transparency and proper processes support both trust and legal compliance.
- This guide is educational; check specific laws in your jurisdiction.
How P2P Crypto Trading Works in Today’s Digital Asset Market
Modern direct-market systems match sellers and buyers through clear offers: asset, fiat, price and payment method. Sellers post terms; buyers select a compatible offer. The platform’s matching engine then facilitates the connection without acting as a traditional fiat intermediary.
Common payment methods include bank transfers, e-wallets and cash deposits. These off-chain steps add flexibility but also create compliance and verification needs for exchanges. Platforms often require proof-of-payment uploads to confirm funds moved outside the digital ledger.
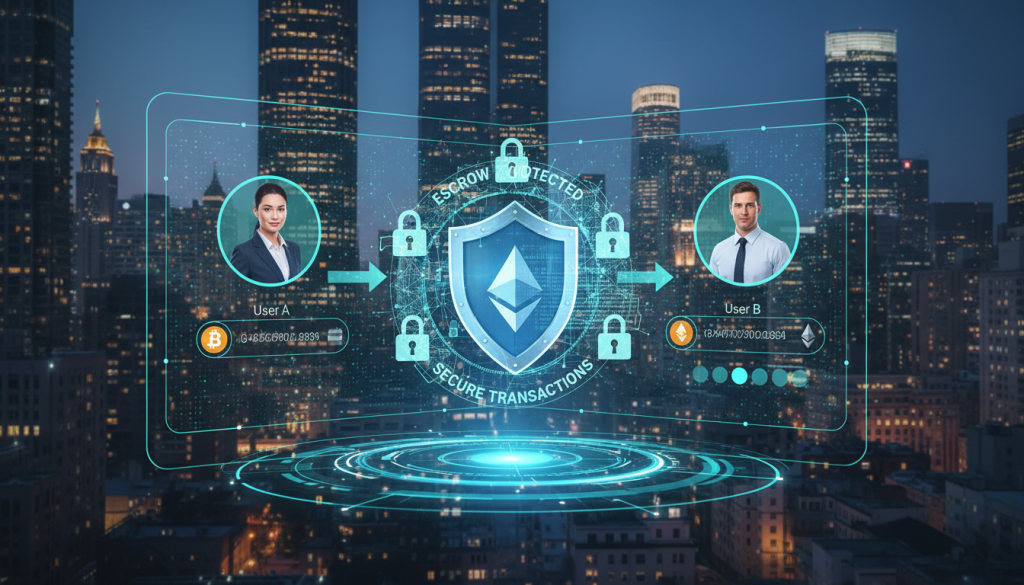
Escrow is the core security layer: the platform locks the digital asset so the buyer can verify payment. Only after the seller’s confirmation—or a successful dispute review—does the escrow release the asset. This reduces counterparty risk and raises user confidence.
Dispute resolution relies on receipts, transaction IDs, chat logs and sometimes AI-assisted review. Timely rules and clear proof standards matter: they protect users and preserve market integrity.
- Reputation systems reward good behavior—ratings and history lower counterparty risk.
- Audit trails store receipts, timestamps and messages to support transparency and later reviews.
- Because platforms enable matching, escrow and dispute outcomes, regulators may see the service as similar to an exchange; operators must balance speed, security and compliance.
For more on compliance expectations and practical steps, see a guide on exchange compliance and an overview of marketplace mechanics: exchange compliance guide and marketplace mechanics overview.
Why Local Regulation Is Tightening Around P2P Platforms in the Present
Authorities now view many direct marketplaces as active financial service operators. That view drives new expectations: platforms must show they can identify users, monitor flows, and report suspect behaviour. These steps aim to prevent misuse while keeping markets open.
Regulators treating platforms like VASPs
VASP means a virtual asset service provider — simply put, any business that facilitates transfers or matching at scale. When a platform meets that definition, authorities expect measures similar to those required of exchanges: customer due diligence, transaction monitoring, recordkeeping and suspicious activity reporting.
Off-chain fiat risks and suspicious activity
Regulators point to off-chain payments as a key risk. Typical concerns include payment reversals, forged receipts, mule accounts and rapid cross-border cycling of funds. These patterns make detection harder and raise money laundering and fraud risks.
- Suspicious activity can mean trades just below reporting thresholds, repeated disputes, or fast in-and-out movements.
- Platforms respond with stronger monitoring, stricter payment rules, and more documentation for high-volume accounts.
- Regulators also expect clearer pricing, better user communications, and reliable complaint handling to protect consumers.
Requirements vary by jurisdiction and change quickly. Exchanges and marketplace operators must design adaptable systems and follow practical guides — for example, see this beginners guide — so they can meet evolving standards across markets.
UAE Snapshot: VARA, Licensing Expectations, and Compliance Signals for P2P Trading
The UAE combines a pro-innovation stance with clear supervisory signals to attract market entrants.
VARA acts as the focal regulator for virtual assets and signals that platforms must show governance, risk controls, and documented procedures—not just technical capability.
Licensing functions as a commercial gateway. Without clear licensing, an exchange can face banking friction, partner reluctance, and limits on onboarding for users and businesses.
Operational readiness and consumer protection
Operational readiness means fast, verifiable onboarding, clear complaint handling, and firm dispute SLAs. These points show regulators that a platform can protect customers.
- Controls: governance, AML, and audit trails.
- Design: permitted payment rails, disclosure standards, and marketing limits.
- Cross-border: geo-fencing, sanctions screening, and terms updates for different jurisdictions.
| Regulatory Signal | Practical Expectation | Commercial Effect |
|---|---|---|
| Governance & controls | Documented policies and risk committees | Better bank and partner access |
| Operational readiness | Onboarding SLAs, dispute processes | Faster user trust and retention |
| Consumer protection | Clear disclosures and allowed rails | Reduced complaints and enforcement risk |
crypto p2p trading local regulations impact on Compliance Requirements
Platform operators must meet exacting verification and monitoring standards to maintain access to banking and partners. These standards shape onboarding speed, risk controls, and daily operations for exchanges serving the UAE and global users.
KYC standards and fast onboarding benchmarks
KYC now often targets sub-five-minute eKYC completion for retail users. Identity data includes name, government ID, selfie checks and proof of address. Automated checks reduce friction while meeting verification requirements.
AML controls, transaction monitoring and KYT
AML is continuous: platforms run transaction monitoring and KYT to flag unusual flows. Risk scoring ties wallet behavior, device signals and trade size into alerts that trigger reviews.
Sanctions screening, blacklist controls and geo-fencing
Exchanges must screen identities and addresses against OFAC, EU and UN lists, apply geo-fencing for high-risk regions, and block sanctioned entities to limit cross-border exposure.
Suspicious activity reporting and recordkeeping
Internal reviews follow alerts; high-risk cases escalate to formal suspicious activity reporting. Retention of chat logs, receipts and timestamps supports audits and regulatory requests.
Data protection and secure retention
Platforms balance audit-ready retention with privacy safeguards: encrypted storage, strict access controls and jurisdictional data handling. Operators targeting the UAE should document policies and keep bank partners informed.
For details on internal privacy controls, see our privacy policy.
Operational Impact on Platforms and Users in the UAE and Beyond
Operational choices now force platforms to balance quick onboarding with documented controls.
Design teams must weigh privacy against usable flows. Stronger compliance reduces anonymity, while many users still expect near-instant access.
That trade-off drives clear UX choices: shorter signup paths for low-risk accounts and stepped verification for higher-value activity. These decisions shape trust and retention.
Fee structures and new revenue drivers
Rising compliance and dispute costs shift monetization. Exchanges often offset expenses by raising trading fees, offering premium dispute services, or selling promoted listings.
Operators also invest in fraud detection and structured proof workflows, which can lengthen timelines but reduce chargebacks and fraud losses.
Proof-of-payment and dispute timelines
Proof workflows become more formal: timestamped receipts, standardized payment references, and metadata checks speed resolution. Well-documented decisions limit legal exposure.
Dispute delays harm user confidence; rushed releases raise scam risk. Consistent documentation and clear SLAs help balance speed and protection.
Account restrictions and enhanced due diligence
Enhanced due diligence triggers include high volumes, repeat disputes, risky jurisdictions, or odd device/IP patterns. Responses range from temporary holds to source-of-funds checks.
These measures protect customers and partners, but they add friction for some users—especially cross-border flows tied to UAE banking relationships.
| Operational Area | Common Measures | Commercial Effect |
|---|---|---|
| Onboarding | Tiered KYC, eKYC checks | Faster low-risk onboarding; extra steps for high value |
| Disputes & proof | Timestamped receipts, metadata verification | Longer resolution times; fewer chargebacks |
| Fees & revenue | Higher trading fees, premium dispute service | Cost recovery; added value for trusted users |
| Account controls | Holds, lowered limits, EDD | Stronger protection; possible user friction |
Global Trends to Watch: How Major Jurisdictions Shape P2P Crypto Rules
Major markets act as trendsetters—their choices shape what platforms offer and how users interact across borders. This regulatory map helps UAE operators decide which features to enable and which to block.
United States
U.S. oversight commonly requires FinCEN MSB registration and BSA duties: KYC/CDD, recordkeeping and suspicious activity reporting. States and agencies such as the SEC or CFTC can layer additional tests or licensing.
Europe
MiCA drives CASP licensing, standardized transparency on pricing and volumes, and clearer user protections. Exchanges face uniform disclosure and reporting guidelines that raise the bar for compliance.
Asia-Pacific
Singapore, Japan and the UAE favour clear licensing and AML/CFT controls. Other countries impose bans or heavy limits—prompting geo-fencing and product exclusions.
Why local rules still matter: each country’s laws shape what features, payment rails and tax reporting platforms can legally offer.
| Region | Focus | Practical effect |
|---|---|---|
| U.S. | BSA, MSB, state licenses | Strict KYC, records, layered oversight |
| EU | MiCA licensing | Uniform disclosures, CASP rules |
| APAC | Licensing vs bans | Geo-fencing, selective services |
- Verify whether an exchange is licensed where you operate.
- Expect KYC in major jurisdictions and stronger AML controls for high-volume activity.
- Plan for tax reporting: rising tax duties push platforms to keep detailed records.
Conclusion
What began as informal person-to-person markets now runs with many of the same controls found at licensed exchanges.
Onboarding, monitoring, payment workflows and recordkeeping now shape the user experience. That change turns casual offers into an exchange-style interaction and raises operational costs for operators.
In the UAE, a pro-innovation stance still demands strong compliance: platforms that invest in governance win faster market access and better partner relations.
Regulators focus on fraud, laundering and sanctions exposure to protect users and preserve market integrity. Expect KYC steps, possible limits, and tax reporting that can add verification friction for users.
For operators, compliance is strategic: it affects product design, pricing and trust. Jurisdictions will keep updating rules, so exchanges and users benefit from following disclosures and tax guidance closely.