Survey: retail buyers in the UAE can lose up to 0.5% of a trade’s value to hidden price differences on small orders. That invisible cost often matters more than visible fees.
The term in focus is the spread: the gap between a buyer’s bid and a seller’s ask. In simple terms, it is an implicit cost embedded in every market price.
For everyday buyers and sellers in the UAE, this gap affects profitability on frequent trades and on illiquid pairs. Liquidity, volatility, fee models, and market-maker activity shape how wide or narrow the gap becomes.
This guide compares order-book markets and P2P quotes, noting that peer quotes can diverge from exchange price for practical reasons like payment method or counterparty risk. The article is informational only and not investment advice.
Readers will get clear, actionable steps: calculate the gap, check order-book depth, and compare platforms before executing a trade.
Key Takeaways
- Spread is the implicit cost between bid and ask prices.
- Wide gaps matter most for illiquid pairs and frequent activity.
- Spreads differ from explicit fees—both affect total cost.
- P2P quotes can diverge from exchange market price for practical reasons.
- Simple checks—calculate gap, view depth, compare platforms—reduce surprise costs.
What a Crypto Spread Means in Real Trades
In live markets, the gap between buyers and sellers shows up every time an order is placed.
Bid price vs. ask price and why the gap exists
Bid price is what buyers are willing to pay. Ask price is what sellers want to receive. The simplest difference between these two is the implicit cost that appears when you enter and exit a position.
This gap exists because traders have different views, liquidity changes, and sellers often demand compensation for immediacy or risk. Fast-moving news or thin participation widens the gap quickly.
How the order book and last traded price shape “market price”
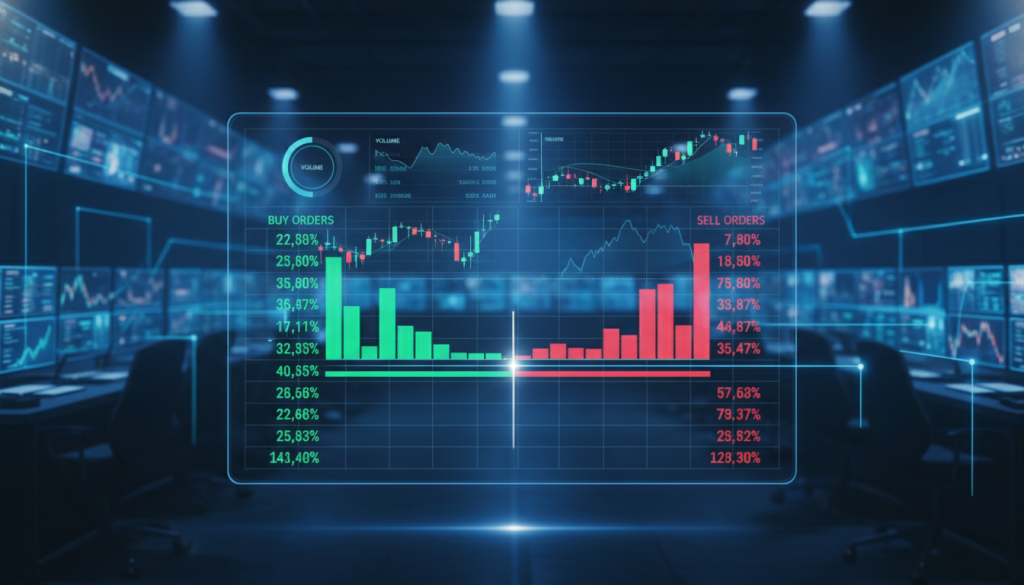
The order book aggregates open buy and sell interest. It shows the highest bid and lowest ask at a glance.
The last traded price records the most recent match, but it does not guarantee the next executable price. Practical market price reference comes from live bids and asks, not a single fixed number.
Quick example: what you lose if you buy and immediately sell
Example: BTC/USDT lowest ask $39,184.93 vs highest bid $39,184.92 — the gap is $0.01.
Another example: if the bid is €29,950 and the ask is €30,000, a buyer who executes at the ask and then sells instantly at the bid loses €50 per BTC from the difference alone. Transaction fees would reduce proceeds further.
| Price point | Value | Notes |
|---|---|---|
| Highest bid | $39,184.92 | Best currently executable buy price |
| Lowest ask | $39,184.93 | Best currently executable sell price |
| Last traded price | $39,184.93 | Most recent match; may differ from next fill |
| Immediate loss example | €50 per BTC | Buy at ask €30,000, sell at bid €29,950 — fees excluded |
For practical steps, readers who want buy bitcoin should check the order book depth before placing a market order. Compare visible bids and asks and consider limit orders to avoid paying the full difference.
Learn more about using gaps and order-book mechanics on this primer: market price and order-book basics.
Crypto P2P Trading Spread Explained for UAE Buyers and Sellers
Local offers can price differently from order-book markets because traders factor real-world frictions into their quotes.
Why peer offers diverge from market quotes
Users on platforms set price to cover payment friction, chargeback exposure, and settlement time. That makes some offers sit above or below exchange listings.
How payment methods widen or tighten prices
Fast, trusted rails often tighten the gap: sellers accept lower markup when settlement is reliable.
Limited options, high fraud risk, or slow bank transfers force sellers to widen prices to cover potential loss. In AED flows, convenience matters to many buyers and sellers.
“Seller willing” vs. “willing pay” in negotiation
“Seller willing” shows the minimum acceptable price; “willing pay” is the buyer’s cap. Final price forms in chat or offer terms and can end between those points.
When a “good deal” hides costs and risk
- Check reputation: low ratings raise counterparty risk.
- Verify proof-of-payment rules: disputes can erase apparent savings.
- Account limits & fees: platform rules may add time or costs.
| Factor | Effect on price | UAE note |
|---|---|---|
| Payment rail speed | Tighter price when fast | Popular local wallets reduce markups |
| Chargeback risk | Wider markup to cover disputes | Sellers price conservatively for card rails |
| Settlement time | Longer time increases premium | Bank delays common in some corridors |
| Platform reputation | Trusted platforms tighten offers | Compare exchanges and platforms before you buy sell |
How to Calculate Spread and Compare Prices Across Platforms
A practical calculation begins at the order book: note the top buy and sell offers and convert that gap into a percent.
The basic formula
Spread = ask price − bid price. On an exchange screen, identify the highest bid and the lowest ask, then subtract to get the raw difference.
Convert to percentage for fair comparisons
Divide the raw difference by the ask price and multiply by 100 to get the percentage spread. This makes comparisons valid across asset price levels.
| Step | Action | Note |
|---|---|---|
| 1 | Find highest bid and lowest ask | On one exchange, refresh live quotes |
| 2 | Subtract ask − bid | Gives the numeric difference (example: $39,184.93 − $39,184.92 = $0.01) |
| 3 | Compute percentage | (difference / ask) × 100 — example: €10/€2,000 = 0.5% |
- Example — BTC: $39,184.93 − $39,184.92 = $0.01; percent is tiny on a high-priced asset.
- Example — low-priced coin: €10 difference on a €200 ask equals 5% — much costlier per unit.
Workflow: check spreads on one exchange, compare with another, then spot outliers versus P2P quotes. Do this close to execution time because market conditions change fast. This method measures transaction friction — it does not predict price direction.
For a deeper primer on peer quotes and negotiation, see the P2P trading primer.
What Causes Wide Spreads in Crypto Markets
Wide gaps in quoted prices usually trace back to how many buyers and sellers are active at a given moment. That activity level—called liquidity—determines how easily an order executes without moving price.
Low liquidity and thin order books
Low liquidity means fewer orders near the mid-price. When the book is thin, a single market order can consume several price levels.
That leads to larger differences between bid and ask and worse execution for traders in less liquid markets.
Volatility and news-driven price swings
Fast news or sharp moves increase risk for anyone placing quotes. Participants widen their quotes to protect against sudden price changes.
As a result, spreads crypto-wide expand during volatile sessions until confidence returns.
Exchange fee models and embedded transaction costs
Some exchanges show low explicit fees but have wider effective pricing; others display tight quotes but add noticeable transaction fees.
Compare both visible fees and effective price impact before choosing an exchange.
Market maker activity and major coins
Market maker activity keeps major cryptocurrencies tightly priced by posting continuous buy and sell quotes.
Smaller coins see less market maker support, so spreads widen more often.
- Practical diagnostic: sudden widening likely signals a drop in liquidity, a volatility spike, or platform-specific conditions.
- Tip: prefer a more liquid market and check order size before placing large orders.
| Cause | Effect | Action |
|---|---|---|
| Low liquidity | Wider spread, higher impact per order | Use limit orders or smaller sizes |
| High volatility | Quotes pulled or widened | Delay execution or reduce size |
| Exchange fee model | Costs hidden in price or fees | Compare effective costs across exchanges |
| Low market maker activity | Tighter pricing absent for small coins | Prefer liquid market pairs |
How to Reduce Spread Costs When Buying and Selling Crypto
Controlling how and when an order is placed reduces the amount paid to the market on each trade. Use a practical playbook to lower costs and improve fills.
Execution choices that matter
Prefer limit orders to avoid crossing the spread. A market order often hits the best opposite quote and can worsen outcomes when liquidity is thin.
Read the order book depth
Look beyond the top quotes. Check how much size sits near current price to estimate slippage and whether a single order will move the market.
Timing and venue selection
Trade during peak liquidity windows to tighten pricing. Choose liquid market pairs and high-volume coins to reduce hidden costs.
- Pick a liquid market pair on reputable exchanges or platforms.
- Use limit orders sized to match book depth near mid-price.
- Compare prices across venues before executing, including local peer offers.
| Action | Why it helps | Practical tip |
|---|---|---|
| Limit order | Controls entry price and avoids crossing the spread | Place slightly inside the book to increase fill chance |
| Check book depth | Reveals slippage risk and hidden costs | Scan cumulative sizes across several price levels |
| Trade high-volume coins | Deeper liquidity and tighter spreads | Prefer major pairs during local peak hours |
Using Spread for Profit: Arbitrage Trading Basics and Reality Checks
Arbitrage captures temporary price gaps across venues and can turn a fleeting mismatch into profit. It includes buying on one exchange and selling on another, routing trades inside a single exchange, or using negotiated offers versus listed prices.
Inter-exchange mechanics
Inter-exchange arbitrage means purchasing an asset on one exchange and selling it where the prices are higher. Paper profit often shrinks after you account for transaction fees, withdrawal costs, and transfer delays.
Intra-exchange and multi-currency chains
Inside one exchange, linked pairs can misprice briefly. Traders use triangular or chain routes to convert assets through intermediate pairs and lock a small profit.
These chains amplify gains but need fast execution and enough capital to cover margins and fees.
P2P arbitrage and negotiated offers
Negotiated offers may diverge from listed prices, presenting an opportunity. However, settlement friction, platform rules, and counterparty limits can eliminate gains.
For background on peer offers and precautions, see this guide: what is crypto p2p trading.
Pay attention checklist
- Fees: maker/taker, withdrawal, and network costs.
- Speed: withdrawal and on-chain confirmation times.
- Limits: minimums, daily caps, and platform holds.
- Tools: execution bots, monitoring connectors, and wallet readiness.
Reality check and risks
Margins on liquid assets are thin, so many traders use bots and capital to scale. Manual attempts face timing uncertainty, price reconvergence risk, software errors, and platform restrictions that can turn planned profit into loss.
| Arbitrage type | Key advantage | Main constraint |
|---|---|---|
| Inter-exchange | Direct price gap across exchanges | Withdrawals, fees, transfer time |
| Intra-exchange chains | Fast settlement, no withdrawals | Complex routing, execution risk |
| P2P arbitrage | Negotiated prices vs listed | Settlement friction, counterparty rules |
Conclusion
Treating the bid–ask gap as a measurable cost makes better decisions more likely. Treat the spread as a measurable cost and build simple checks into every trade plan.
Measure the gap, check order-book depth, convert the difference to a percent, then compare price across venues before placing an order. Remember that a compelling headline price on a peer offer may hide payment friction or platform limits, changing the final result.
When in doubt, use limit orders, trade during higher liquidity windows, and size positions conservatively when spreads widen. For a practical primer on peer offers and safeguards see the beginners guide to P2P trading.